SEC says fake crypto platforms took $37 million from 1,500 Americans, with SEC filings as bait
The SEC sued eight Colorado-registered entities on Thursday. Its complaint says WhatsApp groups steered victims into fake trading apps, then demanded fees to withdraw, while the money moved on to Tron.
Key points
- The SEC sued eight entities in federal court in Colorado on November 19, 2026, saying they used fake crypto trading platforms to take more than $37 million from over 1,500 U.S. investors.
- The complaint says four fake adviser and platform pairs ran from August 2024 to May 2026. Victims sent ETH, USDT and USDC, and the money was routed through bridges to the Tron network.
- Some of the entities made real but routine SEC filings, then showed them to victims as proof of "regulatory approval", the SEC says.
What the SEC says happened
The U.S. Securities and Exchange Commission charged eight entities on Thursday, November 19, 2026, saying they posed as an investment adviser and a crypto trading platform to defraud U.S. investors of more than $37 million. The entities are registered in Colorado but were likely run from overseas, the agency said.
According to the complaint, filed in the U.S. District Court for the District of Colorado, social media ads led people into WhatsApp chats. People in the chats, claiming ties to an adviser, first gave tips on U.S. stocks. Then they urged victims to put as much money as possible into a crypto platform. The platform's app showed growing balances, but the SEC says no real trading took place.
The agency will keep working to "seek out and expose fraudulent investment scams that prey on U.S. investors," said Laura D'Allaird, chief of its Cyber and Emerging Technologies Unit.
Four pairs, one script
The complaint describes four adviser and platform pairs, each dropped after a few months and replaced by the next. It says they received $37,445,800 in all: $35.5 million in crypto and $1.9 million in cash. More than 1,500 U.S. investors were hit.
Crypto received by each fake platform (at least)
US$ million
Source: SEC complaint, Case No. 1:26-cv-06302, paragraph 52.
How the money moved
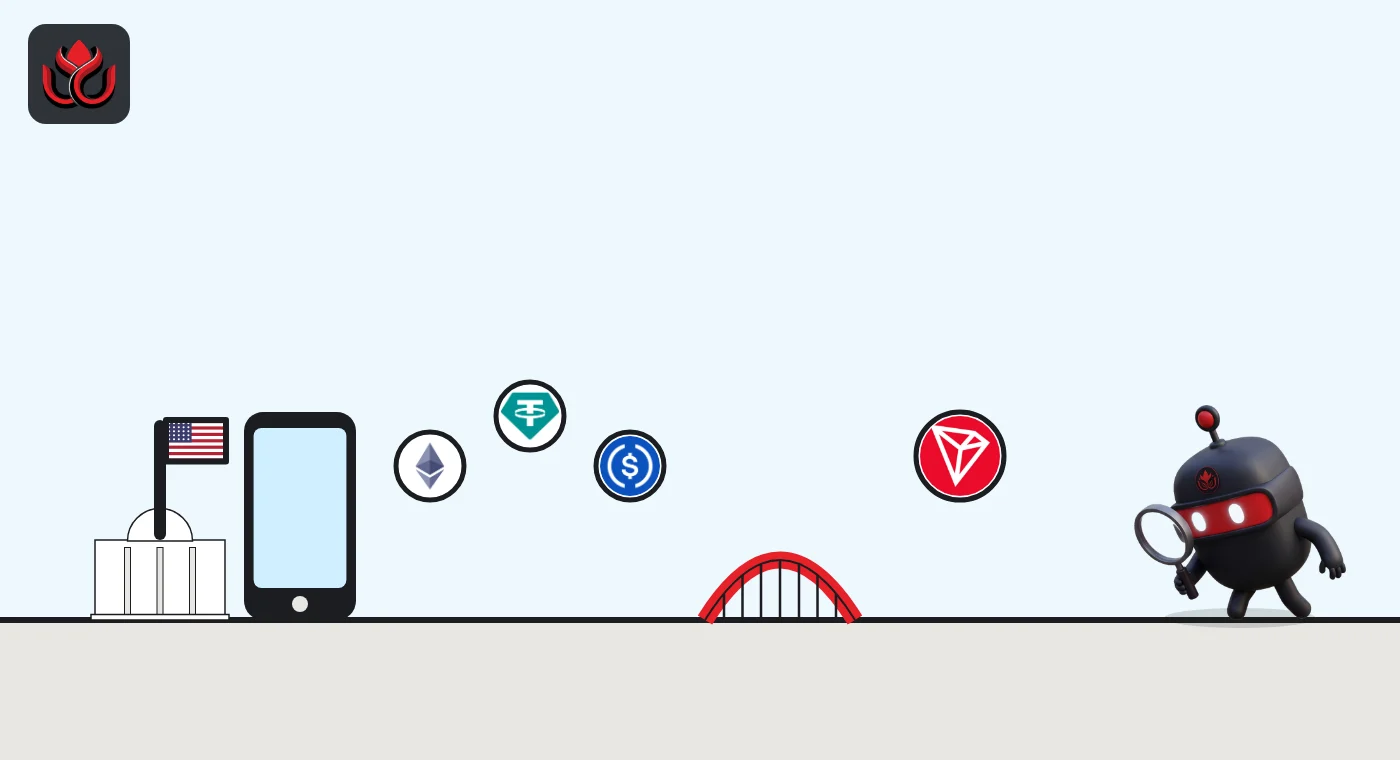
Victims bought crypto on a real U.S. exchange, moved it to a wallet they controlled, and then sent it to an "accumulation address" given by the fake adviser, the complaint says. The schemes took ETH, USDT and USDC.
From four Ethereum collection addresses, the funds went through middle wallets and cross-chain bridges and ended at shared addresses on the Tron network, the SEC says. The money was quickly moved beyond victims' reach.
When victims asked to withdraw their supposed profits, they were told to first pay a fee based on those profits, in crypto, to a different address. The complaint says some were threatened and pressured to pay.
Real filings, fake approval
The SEC says the group used real SEC paperwork as a prop. One platform filed a Form D, a short notice of a private share sale, and its SEC filer number was then shown to investors as proof of registration. Two others filed Forms ADV claiming to be exempt reporting advisers. Victims were also sent made-up SEC "certificates".
None of these filings means the SEC approved or supervises a firm. The agency has removed the filings from its website.
Who lost what
The complaint gives three examples. One investor lost nearly $500,000, including retirement savings and money borrowed from a son and a neighbor. Another lost about $850,000. A third lost close to $1.6 million, including a house and an individual retirement account.
The SEC is asking the court for permanent bans, repayment of the money with interest, and fines. It thanked regulators in Hong Kong, Singapore, China and Switzerland for help.
LC Insight analysis
This section is our reading of the facts above, not a statement of fact.
- We think the most useful detail for readers is the filings trick. A real SEC filer number looks official, but it only means a firm can submit documents, not that anyone checked it.
- The case shows how the money trail can be followed on-chain from Ethereum to Tron, but the SEC does not say any funds were frozen, so recovery for victims looks uncertain.
- Each pair ran for only a few months before being replaced, which suggests the same operators can reappear under new names.
What's next
- Whether the court grants the SEC's requests, and whether any funds are traced and frozen.
- Any criminal charges or overseas action against the operators.
- New platforms using the same WhatsApp and fake-approval pattern.
Disclaimer. This article is based on public information and the sources listed below as of the update time shown. It is for information only and is not investment, legal or tax advice. Figures may change as companies and authorities publish new data.